
Kelly Criterion Calculator: Optimal Bet Sizing & Bankroll Growth (2026)
In professional gambling, sports betting, and algorithmic trading, finding an edge is only half the battle. If you bet too little, you fail to compound your capital; if you bet too much, variance will inevitably drive your bankroll to zero. The Kelly Criterion provides the exact mathematical solution to this dilemma.
The Kelly Criterion formula determines the mathematically optimal percentage of total bankroll to wager on an advantageous bet to maximize the logarithmic growth rate of capital:
f* = (b × p - q) / b, where f* is the fraction of current bankroll to stake, b is the net decimal odds received (payout minus 1), p is the true win probability, and q = 1 - p is the loss probability. Wagering more than Full Kelly (> 2 × f*) produces a negative expected growth rate, making fractional Kelly (0.25x to 0.50x) the standard for risk management.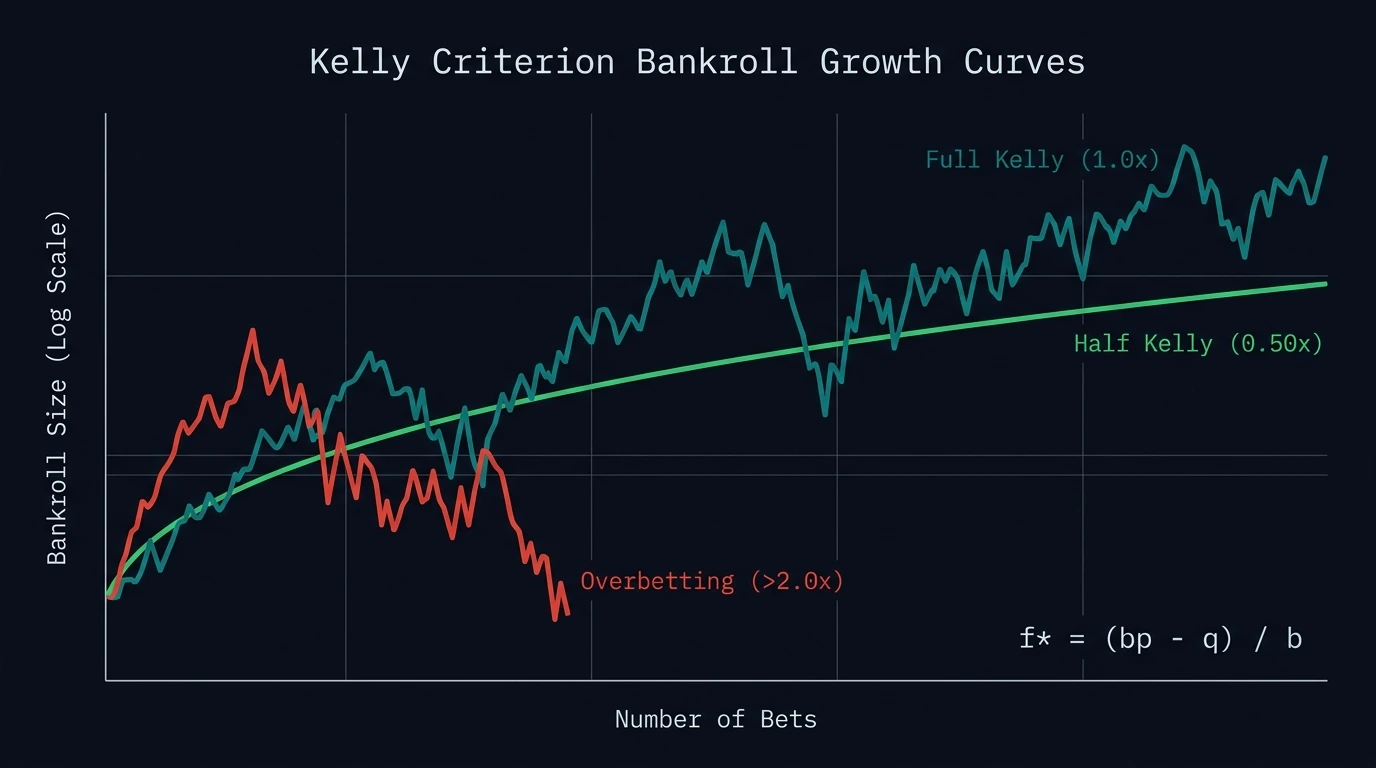
Kelly Criterion Calculator
The Mathematics of Logarithmic Wealth Growth
Developed in 1956 by Bell Labs researcher John Larry Kelly Jr. and adopted by legendary hedge fund manager Edward O. Thorp, the formula maximizes the expected value of the logarithm of wealth:
E[log(W_n)] = p × log(1 + b × f) + q × log(1 – f)
The peak of this logarithmic growth curve represents Full Kelly (f*). It guarantees that asymptotically over infinite rounds, your bankroll will surpass any other staking strategy.
Why Professional Advantage Players Use Fractional Kelly (1/4 to 1/2)
While Full Kelly is mathematically optimal in theory, in reality it produces terrifying volatility:
- A Full Kelly bettor has a 33% chance of suffering a 50% bankroll drawdown before doubling their capital.
- If you overestimate your edge by even a slight margin, betting Full Kelly pushes you into the “Overbetting Death Zone,” where the expected compound growth rate turns negative.
- Half Kelly (0.50x): Achieves 75% of the maximum growth rate while reducing bankroll volatility by 50% and slashing the probability of a 50% drawdown to just 11%.
- Quarter Kelly (0.25x): The industry benchmark for quantitative funds and sharp sports bettors.
Kelly Sizing Across Different Win Probabilities
| Win Probability (p) | Net Odds (b) | Player Advantage (+EV) | Full Kelly (f*) | Half Kelly (0.5x) | Quarter Kelly (0.25x) |
|---|---|---|---|---|---|
| 51.0% | 1 to 1 (Even) | +2.00% | 2.00% | 1.00% | 0.50% |
| 52.5% | 1 to 1 (Even) | +5.00% | 5.00% | 2.50% | 1.25% |
| 55.0% | 1 to 1 (Even) | +10.00% | 10.00% | 5.00% | 2.50% |
| 35.0% | 2 to 1 (3.00x) | +5.00% | 2.50% | 1.25% | 0.63% |
| 20.0% | 5 to 1 (6.00x) | +20.00% | 4.00% | 2.00% | 1.00% |
The Zero Edge Prerequisite: Why Kelly Requires Honest Odds
The Kelly Criterion only recommends placing a bet when bp - q > 0 (positive expected value). If the game has a house edge (negative expectation), the Kelly formula outputs a negative number, directing you to bet $0.00.
This is why high-volume players avoid standard crypto platforms with hidden margins. On Duel Casino, 100% RTP Originals run with 0.00% House Edge, eliminating the negative expectation barrier so that mathematical bankroll sizing operates in true symmetry. Use code VIP to unlock instant VIP Fast-Track privileges.